Financing · Galveston, TX

Fence and gate financing in Galveston

Pay for a new fence or gate over time through GreenSky, Synchrony or Wisetack, subject to credit approval. Get the written estimate first, then compare offers on the numbers that matter.
  • Lenders: GreenSky · Synchrony · Wisetack
  • Reviewed monthly
  • Payment calculator
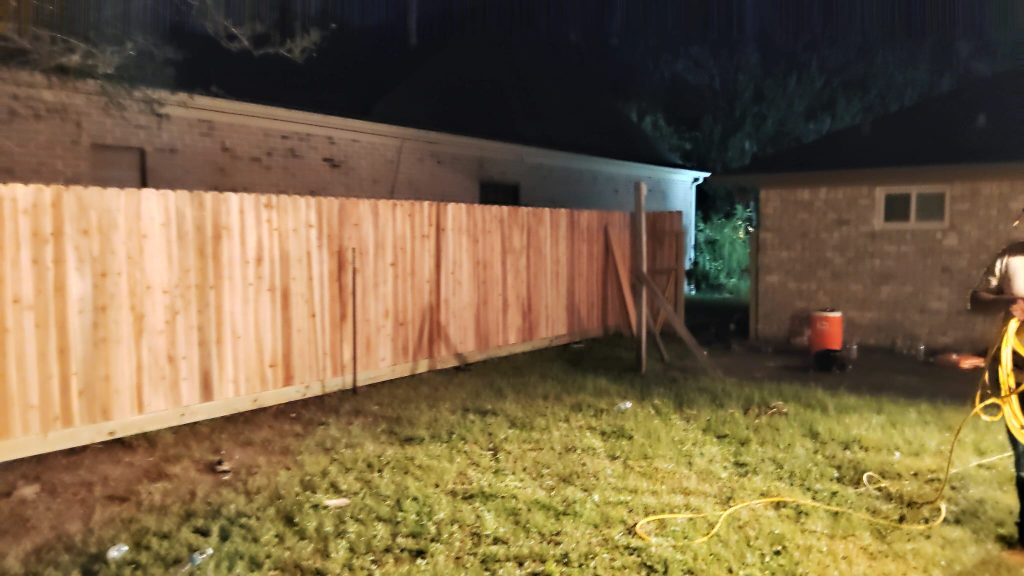
New light wood privacy fence along a back yard at dusk, with a brick house and a worker beside an orange bucket
A new wood privacy fence going in at dusk in League City.
The short answer

Financing for a Mustang fence or gate is offered through GreenSky, Synchrony and Wisetack, and approval and terms are set by the lender, not by us. Start with the free on-site estimate, so you know the amount to finance. Then call (346) 910-8641 and ask about financing. Before you sign, read four numbers on the lender’s disclosure: the APR, the finance charge, the amount financed and the total of payments. If an offer is “0%”, ask whether it is deferred interest.

3Lenders: GreenSky, Synchrony and Wisetack
18Months at 0% APR on Synchrony’s promotion, for qualified applicants
4Numbers every installment-loan disclosure must show (Truth in Lending)
60Days late that can cancel a deferred-interest promotion (CFPB)

Sources: lender list and Synchrony promotion as published on this page; 12 CFR 1026.18; CFPB, deferred interest (reviewed Jan. 22, 2024). Offers change; the lender’s terms when you apply are what count.

Who finances the fence

  • GreenSky: loans for home-improvement projects. Ask which plans are available when you apply.
  • Synchrony: promotional financing; qualified applicants can get 0% APR for up to 18 months. Ask whether that promotion is deferred interest (see below).
  • Wisetack: pay-over-time plans for home services. Wisetack says checking your eligibility doesn’t affect your credit score and that there are no hidden fees.

Each lender decides who is approved and on what terms. We can’t promise approval, a rate or a term.

Payment calculator: read an offer in numbers

Type the total from your written estimate (or keep $1,000 to see the cost per thousand), then the term and APR from the lender’s offer. You get the monthly payment, the total of payments and the finance charge, the same three numbers a loan disclosure shows.

$0PER MONTH
Total
Finance charge
Watch for

Standard level-payment loan math: payment = amount × r ÷ (1 − (1 + r)−n), with r = APR ÷ 12 and n = months; at 0% APR, payment = amount ÷ n. Terms used by 12 CFR 1026.18 (Truth in Lending). Deferred-interest rules from the CFPB. A planning aid only; the lender’s disclosure is the real number.

When to apply

  1. Get the written estimate. The free on-site estimate turns into a written number after the visit: the length of the run, the material, the gates, the posts and any old-fence removal. That number is your amount to finance. Book the estimate.
  2. Ask about financing. Call (346) 910-8641 and tell us which lender you’d like to try.
  3. Read the offer. Check the four numbers in the drawing below, and the promotion type if it says 0%.
  4. Approvals, then the install. Any HOA, historic or city approvals still come first. Financing doesn’t change the rules for the fence.
An example loan disclosure laid out as four boxes: annual percentage rate, the cost of your credit as a yearly rate; finance charge, the dollar amount the credit will cost you; amount financed, the credit provided to you or for you; and total of payments, the amount paid after all scheduled payments. Below them, the payment schedule and a prepayment line. Callouts say to compare offers on APR, that the finance charge is the total of payments minus the amount financed, that the amount financed should match the written estimate less any down payment, and to check for a prepayment chargeFederal Truth in Lending disclosure (example layout)ANNUAL PERCENTAGERATEcost of your creditas a yearly rate__ %FINANCECHARGEdollar amount thecredit will cost you$ ____AMOUNTFINANCEDcredit provided toyou or for you$ ____TOTAL OFPAYMENTSpaid after allscheduled payments$ ____Payment scheduleNumber of payments · amount of each · when they are duePrepaymentWhether a charge may apply if you pay earlyCompare offerson APR, not onthe monthlypaymentFinance charge =total of paymentsminus amountfinancedShould matchyour writtenestimate, lessany down paymentPaying off early:is there a charge?
FN-1
DrawingThe Truth in Lending box: four numbers to read before you sign
Basis12 CFR 1026.18 (b), (d), (e), (g), (h), (k): closed-end credit disclosures
ScaleNot to scale
Federal Truth in Lending rules require these terms, under these names, on an installment loan disclosure. A card-based plan puts its promotional terms in the card agreement instead, so read that for the same things.
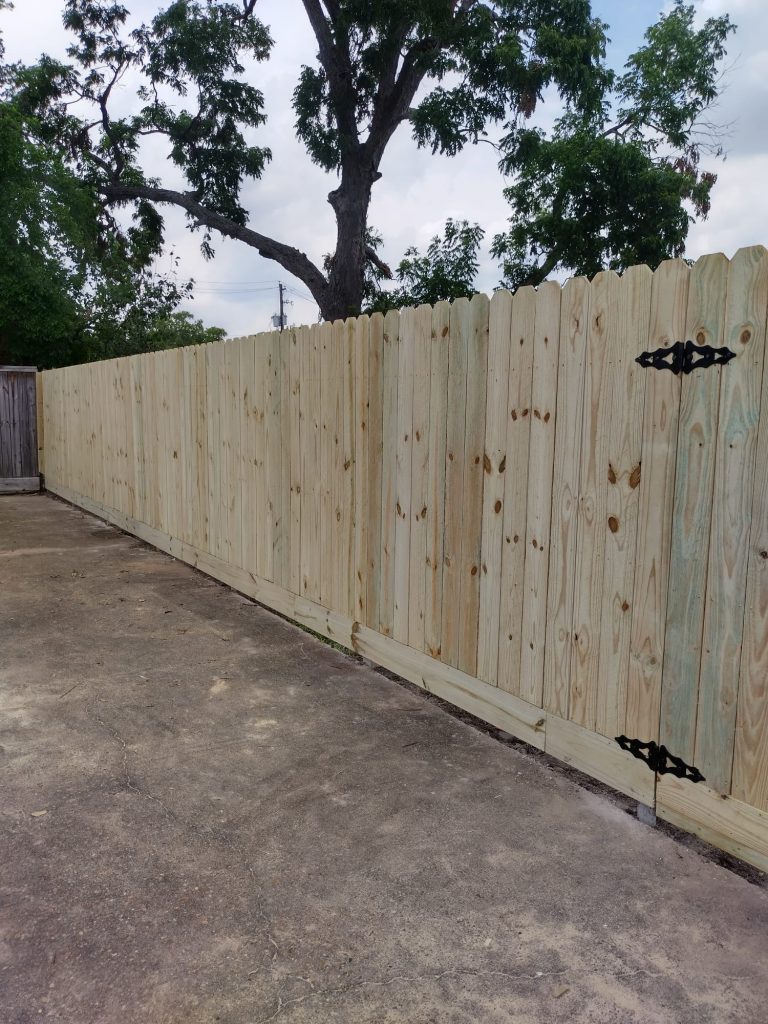
New unstained wood privacy fence with a gate and black strap hinges beside a concrete driveway, under a large oak tree
A new wood privacy fence and gate beside a driveway in Galveston.
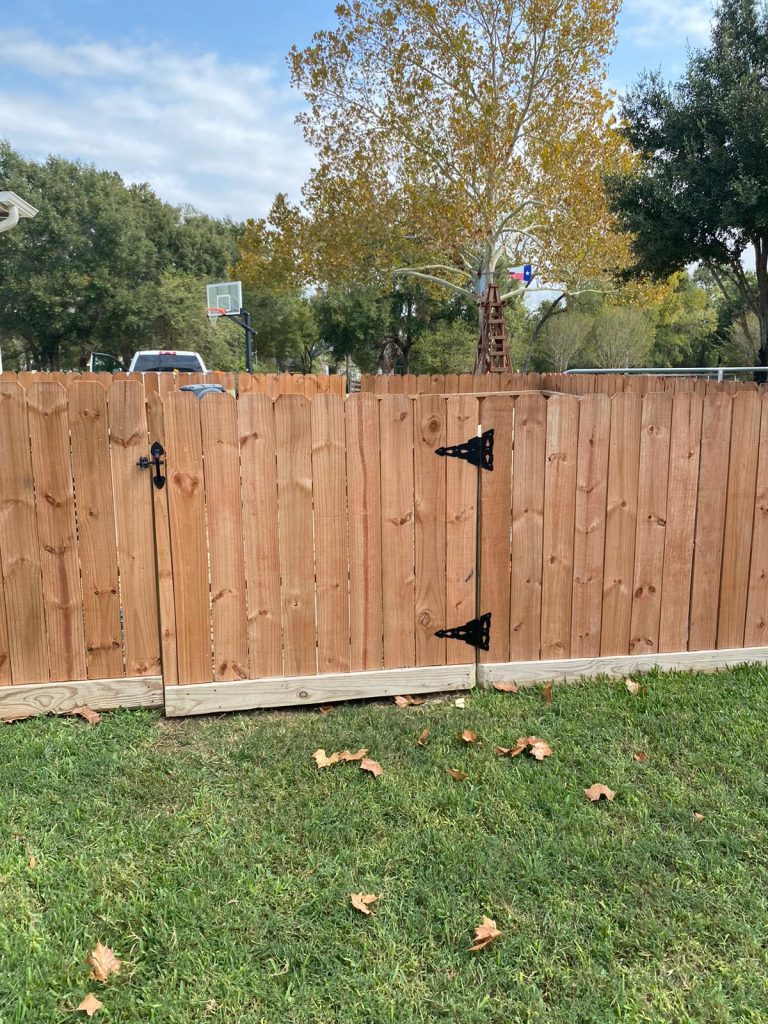
Wood privacy fence with a double gate and black hinges across a lawn with fallen leaves
A wood privacy fence with a double gate in Galveston.
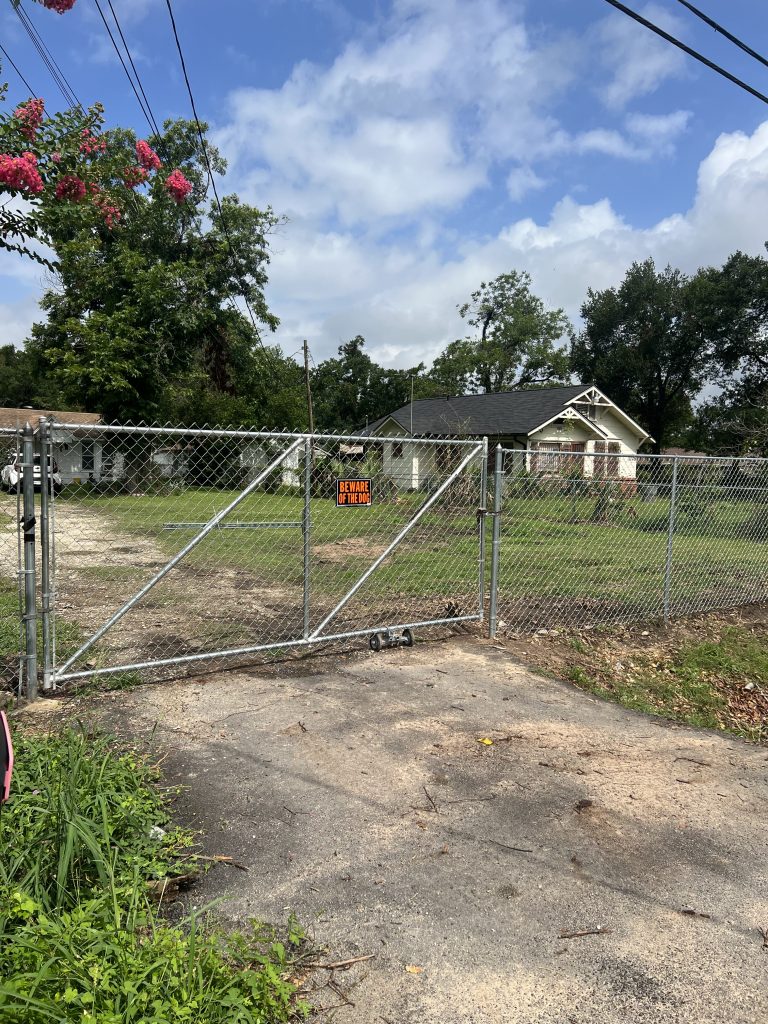
Galvanized chain link drive gate with diagonal bracing across a residential driveway
A galvanized chain link drive gate in Galveston.
Two timelines of a balance being paid down during a promotional period but not to zero. In A, a true 0 percent promotion, interest applies only from the end of the period on what is left. In B, deferred interest, interest is charged back to the purchase date on the balance, plus interest from then onA: True 0% promotion. No interest during the period, whatever is left thenBalancePromotional periodAfter it endsbalance leftinterest from here on, on what’s leftB: Deferred interest. Pay in full in time and it is free; miss it and the interest comes backBalancePromotional periodAfter it endsbalance leftinterest charged back to the purchase dateplus interest from here onBoth lines show a balance not fully paid by the deadline. Paid to zero before the dashed line, both cost the same: nothing in interest.
FN-2
DrawingTrue 0% vs deferred interest: what happens if a balance is left
BasisCFPB, “I got a credit card promising no interest… how does this work?” (reviewed Jan. 22, 2024)
ScaleNot to scale
Under a deferred-interest plan, the CFPB says interest is usually calculated on the balance you owed each month since the purchase. Paying the balance off well before the deadline is what makes it free.

What sets the amount you finance

The amount is the written estimate, less any down payment. The estimate depends on the length and height of the run, the material and style, the number and width of gates, how the posts are set, site access, soil and slope, removing an old fence, and anything an HOA or the city requires. An automatic gate adds an operator, power and an entry device. For automatic gates, automatic gate cost and monthly payments walks through what drives the number. For a side-by-side of the three lenders, see Wisetack vs GreenSky vs Synchrony.

What customers say about the finished work

5.0
91 Google reviews · read them all on Google
★★★★★
Mustang’s team installed iron fence for me and did an absolutely incredible job! I would recommend this company to anyone I know!
Theodore Howitt · Google review · a year ago
★★★★★
Fenomenal job, really nice guy. Contacted them after hurricane knocked down my fence facing the street and got it done really quickly.
Patricia Rios · Google review · a year ago
★★★★★
Installed Stained cedar wood fence yesterday by mustang fencing, thanks for the beautiful work.
Shahrukh Abdul · Google review · a year ago

Reviews shown word for word from the Mustang Fencing Services Google Business Profile (Galveston), captured 2026-10-02.

Questions we get about this

Which companies finance a fence or gate with Mustang?
GreenSky, Synchrony and Wisetack. Each lender decides on approval and sets the rate and term.
Is there 0% financing?
Synchrony offers qualified applicants 0% APR for up to 18 months. Ask whether the promotion is deferred interest: if so, any balance left at the end, or a payment more than 60 days late, usually brings back interest from the purchase date.
Will checking my options hurt my credit?
Wisetack says checking your eligibility doesn’t affect your credit score. For GreenSky and Synchrony, ask the lender whether the application uses a soft or a hard credit check before you apply.
When should I apply?
After the free on-site estimate, when you have the written number. That is the amount to finance, less any down payment.
What should I compare between offers?
The APR, the finance charge, the total of payments and the payment schedule, which installment-loan disclosures must show under federal Truth in Lending rules, plus whether there is a prepayment charge and, for a 0% offer, whether it is deferred interest.
What does the credit cost?
The lender’s finance charge: the total of payments minus the amount financed. It is on the lender’s disclosure, and our calculator shows it for any APR and term you enter.
How do I start?
Call (346) 910-8641 or request a free on-site estimate on the contact page, and ask about financing.

Sources

Checked October 2, 2026. Rules change, so confirm with the City before you build.

  1. 12 CFR 1026.18, Regulation Z (Truth in Lending): content of disclosures — amount financed, finance charge, annual percentage rate, payment schedule, total of payments, prepayment.
  2. CFPB, “I got a credit card promising no interest for a purchase if I pay in full within 12 months. How does this work?” — deferred interest charged on the balance since the purchase; 60 days late; pay more than the minimum.
  3. Wisetack, for consumers — checking eligibility doesn’t impact your credit score; no hidden fees.
Free on-site estimate

Start with the estimate

We’ll measure the line, confirm the rules for your lot and give you a written estimate after a free on-site visit. That’s the number to finance.

Page reviewed October 2, 2026 by Mustang Fencing Services, Galveston. Next review due November 2026.